September payroll processing has brought a significant compliance challenge for Indian HR operations and payroll teams.
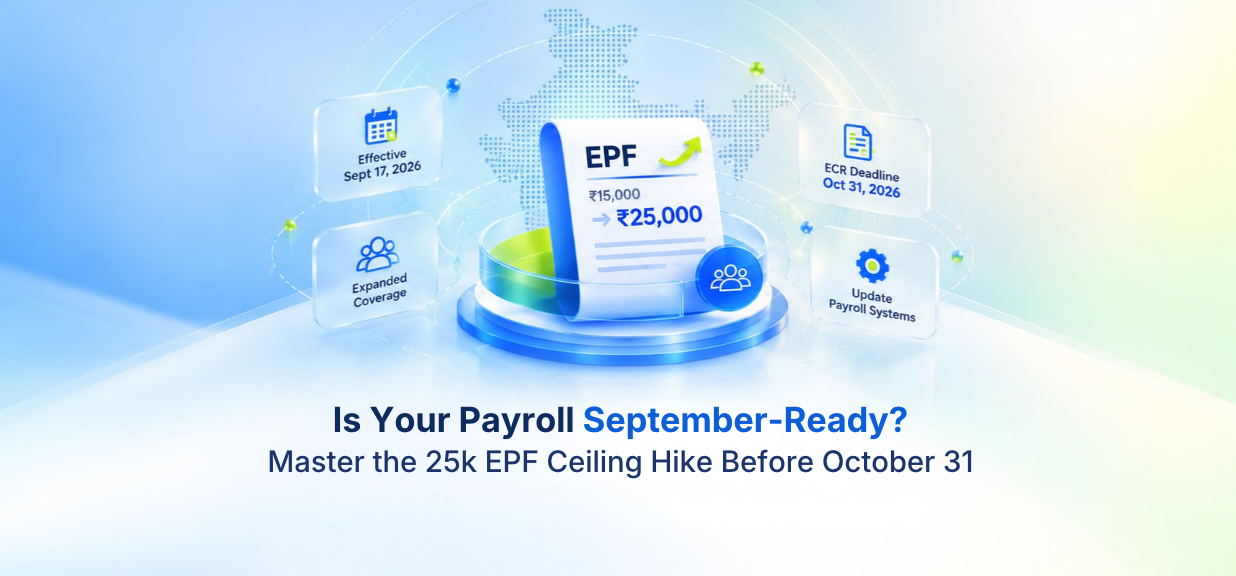
Following the Ministry of Labour & Employment announcement raising the statutory EPF wage ceiling from ₹15,000 to ₹25,000 per month starting September 17, 2026, the Employees’ Provident Fund Organisation (EPFO) extended the September ECR submission and contribution remittance cutoff from October 15 to October 31, 2026.
This extension gives employers vital operational lead time. Whether your team is finalizing salary calculations, processing mid-month adjustments, or preparing file uploads on the EPFO Employer Unified Portal, handling this transition requires careful attention to split calculations, pension allocations, and employee eligibility rules.
Here is a practical roadmap to help your organization complete its September EPF compliance accurately.
1. Mastering the September Split-Period Math for the EPF Wage Ceiling
Because the ₹25,000 wage limit took effect midway through the month (September 17), affected employees’ calculations must reflect the applicable ceilings for two periods:
- Block 1 (September 1 to 16 / 16 Days): Governed by the legacy statutory ceiling of ₹15,000/month.
- Block 2 (September 17 to 30 / 14 Days): Governed by the updated statutory ceiling of ₹25,000/month.
Pro-Rata Working Example (September 2026)
For an existing EPF member with applicable PF wages of ₹25,000 or more per month, employed throughout September with no unpaid days and whose contributions are capped at the statutory limit, the combined wage base is calculated as follows:
| Calculation Window |
Pro-Rata Formula |
Illustrative Contributory Wage Base |
| Period 1 (Sept 1 to 16) |
₹15,000 × 16/30 |
₹8,000.00 |
| Period 2 (Sept 17 to 30) |
₹25,000 × 14/30 |
₹11,666.67 |
| Combined September Base |
Period 1 + Period 2 |
₹19,666.67 |
This example is not a universal calculation. Actual applicable PF wages, membership dates, contribution arrangements, and contributory days determine the calculation for each employee. The prorated amounts are contribution wage bases, not separate membership eligibility thresholds. Apply the prescribed contribution-rounding and ECR reporting rules when preparing the return.
EPFO guidance requires this split-period logic to consolidate into a single ECR upload for September. Ensure your payroll engine does not default to applying a flat ₹15,000 or ₹25,000 cap across all 30 days for affected employees.
2. Recalibrating EPF, EPS, EDLI, and Admin Charges
Raising the statutory threshold reshapes how employer contributions are apportioned between pension funds and provident funds:
- EPS Contribution Limit: For eligible EPS members, the employer’s 8.33% Employees’ Pension Scheme share shifts from a maximum monthly contribution of approximately ₹1,250 to ₹2,083, subject to applicable rules and rounding. Calculate September EPS contributions using the employee’s EPS membership dates, applicable pensionable wages, and period-specific ceilings.
- Employer EPF Share: Employer EPF is calculated as total employer contribution minus the applicable EPS contribution. Do not assume employer EPF is a flat 3.67%, as variations occur for non-EPS members or where EPF and EPS contribution bases differ. Review existing EPF-only members who may become eligible for EPS from September 17, even if their employee PF deduction remains unchanged.
- EDLI & Admin Dues: Re-verify Account 21 (EDLI insurance, subject to the revised ₹25,000 ceiling) and Account 2 (Administrative Charges). Review their applicable wage bases separately, including higher-wage contribution arrangements, and maintain statutory minimum administrative charges per establishment.
3. Re-Evaluating Workforce Eligibility & Coverage
The expanded statutory ceiling brings previously excluded employees under mandatory coverage, subject to establishment applicability and scheme conditions. HR and payroll teams should audit their employee master data against these rules:
| Employee Group |
Applicable Statutory PF Wages per Month |
Required Action |
| Existing Excluded Employees |
Above ₹15,000 and up to ₹25,000 |
Mandatory Enrolment: Enrol eligible employees starting September 17, 2026. Use an existing UAN where available; generate one only where needed. |
| New Joinees (On/After Sept 17) |
Up to ₹25,000 |
Mandatory Enrolment: Enrol eligible employees from their joining date, subject to establishment applicability and scheme conditions. |
| Existing EPF Members |
Any wage level |
Continuous Coverage: Maintain membership and review the applicable contribution base and EPS status. Do not automatically reduce existing higher-wage contribution arrangements to ₹25,000. |
| First-Time Entrants |
Exceeding ₹25,000 |
Excluded Status: May qualify as excluded employees, subject to applicable scheme conditions. Voluntary EPF membership may be available with employer consent. |
4. Pre-Filing Checklist Before October 31
To protect your organization from ECR text file errors, bank clearing bottlenecks, or exposure to applicable statutory interest and damages:
- Audit Wage Definitions: Ensure that elements making up the statutory PF wage base are correctly configured in your payroll software.
- Reconcile Register Figures: Cross-check your split-period calculations against actual payroll registers and net-pay deduction logs.
- Verify Master Records: Ensure member UANs, dates of joining, and exit dates match EPFO records to prevent file upload rejections.
- Aim for an Early Challan Target: As an internal operational target, complete validation and TRRN generation by October 28 to 29. Generating a TRRN alone does not complete the obligation. Complete both ECR filing and successful contribution payment by October 31, 2026, and retain the payment confirmation.
- Set Up October Normalization: Configure your system to apply the revised ceiling throughout October wherever applicable, while retaining the correct employee-specific contribution arrangements. The ordinary deadline is November 15, 2026, subject to subsequent EPFO instructions.
Simplifying Compliance with Modern Payroll Architecture
Mid-cycle regulatory changes highlight why traditional payroll setups can lead to administrative friction. Managing split calculations, pro-rated caps, and dynamic membership rules requires an agile global payroll tech stack with built-in effective-date controls and automated compliance updates.
At Neeyamo, we specialize in global payroll and statutory compliance operations. Our enterprise platform helps organizations manage complex multi-country requirements, supported by payroll automation and local compliance expertise, reducing manual effort and strengthening payroll controls.
If you want to streamline your statutory compliance engine or upgrade your global payroll infrastructure, our team of experts is ready to assist.
Write to irene.jones@neeyamo.com to learn how Neeyamo can simplify your global payroll and compliance operations.